03.11.25 | For Buyers

Ontario’s Housing Market Heating Up, Prices on the Rise

Ontario’s real estate market kicked off 2025 with a bang, as home prices surged with more buyers willing to step into the market. In just six weeks, the average home price surged nearly 8%, driven by pent-up demand and favorable economic conditions. We believe this trend is taking shape and will play a key role in the upcoming spring market. Here’s why.

The Numbers: A Rapid Price Surge and Sales Volatility

Since the first week of January, Ontario’s housing market has been on a surprising upward trajectory. In Week 1, the average home price stood at $799,780, but by Week 5, prices had jumped to $845,719—a gain of over $45,000 in just one month. As of the latest data, the average price has climbed further to $862,297, with a brief peak of $870,102 in Week 6 before modest stabilization.

Sales activity tells a similarly dynamic story. Initially, only 1,112 homes were sold in Week 1, but buyer enthusiasm quickly intensified, driving sales to 2,409 by Week 5 and a high of 2,490 in Week 6. However, recent weeks have seen a slight cool down, with transactions dipping to 1,762. Despite this pullback in sales volume, prices remain elevated due to persistently low inventory and competitive bidding.

What’s Fueling the Frenzy?

Stabilizing interest rates and optimistic economic forecasts are luring many buyers back into the market. The Bank of Canada’s decision to cut rates to 3%—a historic low—has made mortgages more affordable, encouraging first-time buyers and investors to rethink their decision to hold off.

Ontario’s surging home prices stem from three key drivers: seasonal demand, investor activity, and delayed market adjustments. The start of the year typically sparks a rush of buyers aiming to purchase before spring’s peak competition, while investors add pressure by snapping up properties for rentals or resale, shrinking inventory and fueling bidding wars. Meanwhile, after a sluggish late 2023, where prices stagnated, the market is now playing catch-up, with values climbing rapidly to reflect today’s imbalance of high demand and low supply. Together, these forces are pushing prices upward at an unprecedented pace.

The Role of Interest Rates

The Bank of Canada’s rate cuts have been a game-changer. By reducing borrowing costs, the central bank has injected fresh liquidity into the housing market. For many buyers, this has lowered the barrier to entry, particularly for those who had been sidelined by higher rates in previous years.

What’s next for Ontario’s Housing Market?

Experts predict the upward price trend will persist in the short term. With demand outstripping supply and interest rates remaining favorable, analysts project the average home price could reach $900,000 in the coming weeks. However, the recent dip in sales—from 2,490 in Week 6 to 1,762—suggests that affordability concerns may begin to temper activity. Yet, as long as inventory remains tight, prices are unlikely to decline significantly.

Advice for Buyers and Sellers

For buyers, the window to act is narrowing. Securing a mortgage at current rates could save thousands compared to waiting for potential rate hikes later this year. Pre-approvals and swift decision-making are essential in this competitive environment.

Sellers, on the other hand, are in a strong position to capitalize on rising demand. Pricing strategically and staging homes effectively can maximize returns, especially as bidding wars become more common.

A Market at a Crossroads

Ontario’s housing market is at a pivotal moment. While prices continue to climb, the slight slowdown in sales signals that affordability pressures may soon test the market’s resilience. For now, buyers and investors are racing to lock in deals before costs rise further while policymakers grapple with balancing growth and accessibility.

One thing is clear: In a market such as this, staying informed and agile is the key to success. Whether you’re buying, selling, or simply watching, Ontario’s real estate landscape promises to remain a headline-maker in 2024.

Source: The Canadian Home
02.12.25 | For Buyers

Selling Your House in the Winter

When winter rolls around, many people assume the real estate market goes into hibernation. But if you’re considering selling your house in the winter, there’s no need to wait. In fact, selling a house in winter vs spring comes with unique benefits. With fewer homes on the market and more motivated buyers, winter could be the perfect time to list your home and reap some unexpected financial rewards.

Less Competition Means More Attention

Because there aren’t as many homes on the market during winter, that’s a huge plus for sellers. In the busy spring and summer months, your property can get lost in a sea of listings. When selling your house in winter, it is more likely to get the spotlight. Serious buyers are scrolling through fewer options, and your property has a better chance of catching their eye. If you price your home right and make it look inviting, you’ve got a real shot at standing out. But don’t overprice your home, thinking buyers are desperate—it can backfire. People are still doing their homework. And don’t forget to update your listing photos to reflect the season. A snow-covered yard might resonate more with buyers in January than a lush, green lawn from last summer.

Winter Buyers Mean Business

Do houses sell in the winter? Absolutely! Buyers who are shopping at this time of year are often the most motivated and less likely to back out of the deal. They’re likely relocating for a job, taking advantage of tax benefits, or facing life changes that can’t wait. These aren’t casual browsers. They’re ready to make decisions quickly, leading to faster offers and smoother negotiations. These buyers often have tight schedules, so flexibility is essential. Be sure to prepare your home for winter. If your home is hard to access, say, due to bad weather, it could deter them. Keep driveways and walkways clear and safe to ensure buyers can view your home without hassle.

Your Home’s Strengths Shine in Winter

Winter weather puts your home’s durability to the test, which can work in your favour. A warm, dry, and inviting house creates a lasting impression, especially when buyers are looking for comfort during colder months. Practical features like energy-efficient windows, a reliable heating system, and advanced energy solutions can set your home apart in the winter market. A well-maintained roof, clean gutters, and a tidy exterior show that the property is well cared for and prepared to handle any season. Address any winter maintenance issues like drafty windows or uneven heating before showings, because buyers will notice.

Winter Warmth Sells

Winter’s chill is the perfect backdrop to showcase your home’s cozy, inviting vibe. When selling a house in winter, warm lighting, comfy blankets, and even a crackling fireplace can turn your space into a haven buyers will fall in love with. Don’t go overboard with holiday decorations. A simple wreath or a bowl of pinecones can create charm without overwhelming the space.

Quicker Sales Are on the Table

Selling a house in winter vs spring can mean faster transactions. You don’t need to wonder, “Do houses sell in the winter?” They do, and often with unique advantages. With fewer homes on the market, buyers are pushed to act quickly, and real estate professionals like agents, inspectors, and appraisers often have more availability during this time. This can lead to quicker closings and less waiting around. However, avoid rushing into accepting an offer without considering it carefully. Some buyers may try to negotiate aggressively, thinking winter sellers are more eager. Stay firm and work with your agent to get the best deal.

Financial Benefits of Selling in Winter

Selling your house in the winter could have financial perks. Closing a deal before December 31 may allow you to offset capital gains with other investment losses for the year, reducing your taxable income. Expenses like real estate commissions, staging, or upgrades made to prepare your home for sale can also reduce your taxable gain, helping you save money. Tax rules can vary based on your situation, so consulting a tax professional is always a good idea. They’ll help you understand your deductions so you can take advantage of every financial benefit available. Keep detailed records of all selling-related expenses for easy reporting to the CRA.

Selling a house in winter doesn’t have to be a challenge. It can be a golden opportunity. At RE/MAX, we bring the expertise, tools, and local knowledge you need to maximize your home’s potential. Whether it’s working with motivated buyers, highlighting your home’s cozy charm, or leveraging the unique perks of selling a house in winter vs spring, we’re here to guide you. Contact your local RE/MAX agent today to make the most of your winter sale!

Source: Re/Max Canada

12.12.24 | For Buyers

BoC Implements Second Consecutive Large Rate Cut

Benchmark Interest Rate Now Set at 3.25%

In a widely anticipated move, the Bank of Canada (BoC) has followed up its previous rate cut with another half-point reduction to its benchmark interest rate, which now stands at 3.25%. This is the fifth consecutive rate cut, despite a slight uptick in inflation, which rose to 2% in October from 1.6% in September. While inflation remains at the BoC’s target, the central bank has expressed growing concerns about the overall health of the economy.

Interest Rates and the Canadian Housing Market

Looking ahead to 2025, the housing market in Canada is expected to rebound, according to the latest report from RE/MAX Canada. The positive outlook is fueled by a series of interest rate cuts in the latter half of 2024, with more rate reductions predicted in 2025. As buyers are expected to return to the market, sellers have begun listing more properties. The national average residential price is forecast to rise by 5% next year, with home sales projected to increase in 33 out of 37 major markets, in some cases by up to 25%.

Despite ongoing affordability challenges, the series of interest rate cuts and adjustments to the mortgage stress test are providing much-needed relief for prospective buyers, particularly first-time homebuyers. However, an uptick in sales combined with limited housing supply is likely to drive prices higher, a trend that is expected to emerge across most Canadian housing markets.

According to Christopher Alexander, President, RE/MAX Canada

Bank of Canada’s 2025 Policy Interest Rate Schedule

The Bank of Canada announces its overnight rate target eight times a year, usually on Wednesdays. The schedule for 2025 is as follows:

  • Wednesday, January 29
  • Wednesday, March 12
  • Wednesday, April 16
  • Wednesday, June 4
  • Wednesday, July 30
  • Wednesday, September 17
  • Wednesday, October 29
  • Wednesday, December 10

Full Interest Rate Announcement:

The Bank of Canada has reduced its target for the overnight rate to 3.25%, with the Bank Rate at 3.5% and the deposit rate at 3.25%. This decision is part of the Bank’s ongoing efforts to normalize its balance sheet.

The global economy is largely evolving as expected, according to the BoC’s October Monetary Policy Report (MPR). In the United States, the economy remains strong, supported by robust consumer spending and a solid labor market, though inflationary pressures persist. In Europe, growth indicators have weakened, while in China, a combination of policy actions and strong exports is driving growth, though household spending remains subdued. Globally, financial conditions have eased, and the Canadian dollar has depreciated against a stronger US dollar.

In Canada, the economy grew by 1% in the third quarter, slightly below the BoC’s previous forecast, and the outlook for the fourth quarter remains weaker than anticipated. Business investment, inventories, and exports all contributed to the softer growth, while consumer spending and housing activity showed signs of improvement, suggesting that lower interest rates are beginning to boost household spending. Revisions to historical GDP data also indicate that investment and consumption have been higher than previously reported.

The unemployment rate rose to 6.8% in November, as employment growth lagged behind the increase in the labor force. While wage growth showed some signs of easing, it remains elevated relative to productivity.

Several government policy measures, including reduced immigration targets and changes to the GST and mortgage rules, will have an impact on growth and inflation in Canada. While these measures are expected to dampen demand, the BoC is focusing on long-term trends in its policy decisions.

The Bank of Canada notes that core inflation has remained close to the 2% target since the summer, with shelter-related price pressures moderating and goods prices also easing. The temporary GST holiday is expected to lower inflation in the short term, but this effect will reverse once the holiday ends.

Given that inflation is holding steady at around 2% and the economy is operating below potential, the BoC has reduced the policy rate by 50 basis points to stimulate growth and ensure inflation stays within the target range. The central bank will continue to monitor economic conditions and adjust its policy as necessary to maintain price stability.

Source: Re/Max Canada

11.14.24 | For Buyers

Canadian Real Estate: What to Know Before You Buy

There’s no denying that Canadian real estate is valued, on many different levels. Owning is a way to plant roots, create security and build wealth. In fact, investing in the housing market how many of the world’s richest people have earned their fortunes, and it’s how many Canadians finance their retirement or build generational wealth.

Ultimately, the decision to buy a home is a very personal one that depends on a number of factors, such as your financial fitness, your lifestyle and your future plans. The good news is, professional real estate agents, mortgage brokers and real estate lawyers are there to advise you as you dive in. Here are some important things to consider, to help get you thinking about whether buying a home in the current Canadian real estate market is right for you.

5 Questions to Ask Before Buying Canadian Real Estate

Can I afford to buy Canadian real estate?

Buying real estate involves up-front costs, which can include things like your deposit, down payment, home inspection and appraisal fees, property insurance, land transfer tax, title insurance, legal fees and moving expenses. Click here to explore the cost of home ownership.

Then, there are ongoing costs that include property tax, regular maintenance, condo fees if you choose this type of property, and utilities. If you’re saving some money up-front by buying a fixer-upper, you’ll also need to also factor in renovation costs at some point.

Here are some strategies to spend less, and save more.

Do I have too much debt?

When buying real estate, most people will take on a mortgage. Lenders evaluate your costs versus income to determine your qualification. Your Gross Debt Service ratio is your housing costs (mortgage principal and interest + property taxes + heat + 50% of your condo fees, if applicable) divided by your pre-tax income. According to Canada Mortgage and Housing Corp., your GDS ratio should be 39% or less.

Then, lenders look at your Total Debt Service ratio: all debt (GDS + car payments + alimony + other loans + the remaining 50% of your condo fees) divided by your pre-tax income. CMHC says your TDS ratio should be less than 44%.

Click HERE for to calculate your GDS and TDS.

Am I secure in my job?

Think about this honestly. Is business bustling? Is the industry in a growth period or is it on the decline? Are you comfortable with the hefty and lengthy financial commitment of home ownership?

Speak to your supervisor to get some additional insight. Mortgage lenders like to see stable employment, and you’ll need to provide proof of income in the form of an employment letter or current pay stub, your position and length of employment, and if you’re self-employed, Notices of Assessment from the Canada Revenue Agency for the past two years.

Click HERE to find out what else mortgage lenders look for.

Am I sticking around?

Buying real estate has historically proven to be a good long-term investment. Ask your parents how much they paid for their home 30 years ago, and compare that to current market value. Changed are, their investment has grown. On the other hand, a quick sale can mean financial losses if the home’s appreciation doesn’t surpass closing costs, which are estimated at 1.5% to 5% of a home’s value.

Typically, the magic number to stay in the home before putting it back on the market is five years – hence the five-year plan.

Do I even want to own a home?

People invest in the Canadian real estate market for a slew of different reasons. For homeowners, this is a method of forced savings for retirement and future generations, while also fulfilling the basic need of providing shelter. It’s also a great source of pride for many. Picture yourself in five years. Do you plan to relocate at some point? Where will you work? What’s your family structure? Then, consider how home ownership fits into the bigger picture.

Thinking about making a move? We can help you determine what the best strategy is for you and your family. Reach out to us today.

Source: Re/Max Canada

10.11.24 | For Buyers

Government Unveils Boldest Mortgage Reforms in Decades to Enhance Homeownership Opportunities for Canadians

Canadians put in significant effort to afford a home, but high mortgage payments pose a challenge, particularly for Millennials and Gen Z. To assist younger generations in purchasing their first homes, new mortgage regulations took effect on August 1, 2024. These rules allow for 30-year insured mortgage amortizations specifically for first-time buyers of new constructions.

Chrystia Freeland, Deputy Prime Minister and Minister of Finance unveiled a range of reforms aimed at making mortgages more affordable and promoting homeownership among Canadians:

  1. Increasing the Insured Mortgage Cap: The cap for insured mortgages will rise from $1 million to $1.5 million, effective December 15, 2024. This adjustment reflects current market conditions and aims to help more Canadians qualify for a mortgage with a down payment below 20 percent. The cap has remained unchanged since 2012.
  2. Expanding Eligibility for 30-Year Amortizations: Starting December 15, 2024, all first-time homebuyers and buyers of new builds will be eligible for 30-year mortgage amortizations. This will lower monthly mortgage payments and encourage the purchase of new constructions, including condos. This initiative builds on the commitment from Budget 2024, which also introduced 30-year amortizations for first-time buyers of new builds.

These initiatives are part of the enhanced Canadian Mortgage Charter, introduced in Budget 2024, which allows insured mortgage holders to switch lenders at renewal without undergoing another stress test. This change promotes competition among lenders and allows more Canadians with insured mortgages to secure better deals.

These reforms represent the most significant changes to mortgage regulations in decades and align with the federal government’s ambitious plan to create nearly 4 million new homes—Canada’s most extensive housing initiative ever—to support homeownership.

In tandem with efforts to improve mortgage affordability, the government is also taking strong measures to safeguard the rights of homebuyers and renters. As part of Budget 2024, the government has presented plans for a Renters’ Bill of Rights and a Home Buyers’ Bill of Rights. These proposals aim to protect renters from unfair practices, simplify lease agreements, enhance price transparency, and make the home-buying process more equitable. The government is collaborating with provinces and territories to implement these plans, utilizing $5 billion from the new Canada Housing Infrastructure Fund. This initiative includes calls for measures to prevent renovictions, ban blind bidding, standardize lease agreements, and ensure sales price history is accessible through title searches, all aimed at creating a fairer housing market across Canada.

Thinking about making a move? We can help you determine what the best strategy is for you and your family. Reach out to us today.

11.7.23 | For Buyers

What Does a Real Estate Lawyer Do?

Do you ever wonder why your favourite movie stars always look so good? Or why your local coffee shop is always spotless and decorated for the season? The reason is simple: they have a team of professionals who meticulously arrange every detail.

Before you start wondering how this relates to your home-buying journey, think about all the professionals you have standing behind you as you search for your dream home. Besides your real estate agent, you have a whole team helping guide you home, including a real estate lawyer.

What Does a Real Estate Lawyer Do for the Buyer?

Buying a home is likely the most significant transaction you will make in your lifetime. This life-altering decision requires the support of professionals to make sure that every step of the process is followed, ensuring that every “i” is dotted and every “t” crossed.

The person who takes care of the dotting and crossing on every legal document is your real estate lawyer. If you’re new to the home buying experience, you probably know you need a lawyer but may not be sure what role they play.

A real estate lawyer is necessary both for the buyer and seller. We’ll start with their role on the buyer’s side. They ensure the transfer of ownership, outlining the terms of your purchase agreement and a clear title to the property. That is their role at the most basic; it goes far beyond, including the following:

  • Review the Agreement of Purchase and all other legal documents
  • Ensure there are no claims listed against the property
  • Arrange for Title Insurance
  • Ensure you have a valid title upon closing
  • Ensure property taxes are up to date
  • Calculate the land transfer tax due on closing
  • Draw up the mortgage documents
  • Close the transaction and ensure all legal and financial conditions are met
  • Exchange legal documents and keys with the seller’s lawyer

What Does a Real Estate Lawyer Do for the Seller?

The real estate lawyer’s role on the seller’s side is also related to ensuring the transaction goes smoothly and that all legal aspects are covered. They are focused on the mortgage payout and a smooth transfer of the property’s title. Just like on the buyer’s side, a real estate lawyer performs several key tasks, including:

  • Review the Agreement of Sale and other legal documents before you sign
  • Assist you with the negotiation of the terms and conditions
  • Prepare the deed to your house
  • Deal and remedy title issues as they occur
  • Close the transaction
  • Ensure all legal and financial conditions have been met
  • Exchange legal documents and keys with the Buyer’s lawyer

When Do You Need a Real Estate Lawyer?

Whether you are buying or selling a home, you will need a real estate lawyer to register the transfer of property with your province’s land registry office. You are required to have a lawyer because lawyers can access Provincial Electronic Land Registration Systems. Every province has different regulations, but a legal professional must register a property and purchase a home to ensure it is legal.

While many real estate transactions in Canada use standard form agreements prepared by realtors, a lawyer will review and amend these contracts to ensure they cater to specific needs or situations. They can also conduct a title search to ensure there are no liens or other encumbrances on the property and help you understand and secure title insurance, which is becoming increasingly common in Canada.

How a Real Estate Lawyer Can Help with Complications

A real estate lawyer is indispensable when a housing deal faces complications, such as when a property is appraised at a value lower than the agreed offer. The attorney can provide clarity on the contractual implications of such a scenario. Many real estate contracts contain appraisal contingencies that allow the buyer to renegotiate or withdraw from the purchase without penalty if the appraisal is low. The lawyer can review the terms and advise on potential avenues of action. If both parties remain keen on completing the sale, the attorney can facilitate negotiations, ensuring that any new terms or price adjustments are legally sound and in the best interest of their client. A real estate lawyer can also investigate if the appraisal was conducted accurately and fairly, providing grounds for a potential challenge or request for a second opinion.

Can a Real Estate Lawyer Represent the Buyer and Seller?

In real estate transactions, it’s generally considered a conflict of interest for a single lawyer to represent both the buyer and the seller. This is because the interests of the buyer and the seller can often be at odds. The seller aims for the highest price and best terms, while the buyer typically wants the opposite. A single attorney representing both parties can be put in a difficult position, trying to serve two masters with diverging goals. Dual representation also increases the risk of malpractice claims, as either party might later believe they were inadequately represented if the deal goes awry. Each party deserves an advocate who can negotiate and advise with their best interests in mind. This becomes compromised when one lawyer tries to balance the needs of both parties.

Now that you better understand the real estate lawyer’s role, it’s time to choose one that will best represent you throughout the transaction. Choosing a real estate lawyer is something The Barnett Real Estate Team can help you with, as they often work closely with trusted professionals.

01.31.22 | For Buyers

Is It Better to Buy or Rent in Canada in 2022?

Many Canadians who currently rent are dreaming of homeownership. If you fall into this camp, you may be wondering whether 2022 is the time to make your dream come true. The truth is, there are many things to consider—including which option will most benefit you financially. 

If you’re trying to decide whether to buy or rent the next place you call home, here’s what you should know…

The current market

When you’re thinking about buying, it’s important to understand local market conditions. There’s no doubt that we’ve been in a seller’s market for some time now, and (while we certainly can’t predict the future) there’s no indication that this trend is going to change anytime soon. 

While 2022 has just begun, last month’s numbers can provide us with some much-needed insight. In Halton Region, the average home price is on the rise—and for December, it reached $1.34 million. In Milton, it was nearly $1.35 million, and in Burlington, it was $1.23 million.

In other words, it’s hard to get a foot in the market right now. Given the sums of money involved, it’s critical to think your decision through. That said, if you have the time and resources to compete, there are some substantial benefits to doing so. 

From long-term appreciation to greater financial security, there are many reasons why so many buyers can’t wait to take this step—even if it means starting with a small condo when they’re looking forward to buying a house. Let’s take a closer look at the financial advantages of purchasing a piece of real estate right now.


The first step towards buying a home is making sure you’re informed. You’ll find in-depth information about what the process is like right now in our recent blog posts below.


The financial perspective

Studies frequently show that in most cases, owning a home is more financially beneficial than renting in the long run. To start with, as The GTA’s population grows, so too does the number of people who need a place to live. That’s putting rentals in high demand, so it’s no surprise that rents are on the rise. Unfortunately, when you pay this monthly cost, your money doesn’t work for you. It helps your landlord pay their mortgage.

If, on the other hand, you decide to buy, a significant portion of your mortgage payments will go towards your principal. In a sense, it can be considered a forced savings account (since you’re constantly building equity). When you look at it this way, you can see how monthly rent can be significantly more costly than your mortgage payments. 

When it comes to improving your financial situation, owning a home gets even better. You’ll not only benefit from equity but long-term appreciation. In the vast majority of cases, local real estate becomes more valuable over time. While the market fluctuates, it also bounces back—and an experienced agent can help you get top dollar when you’re (eventually) ready to sell.

Buying a home also gives you the opportunity to bring in passive income if and when you decide to move into another home. By renting out the living space you buy, you can grow both your bank account and your personal net worth. Having an investment property is also a great way to diversify your portfolio. 

Ready to learn more about the purchase process? Start by downloading our buyer’s guide right here.

Your long-term priorities

Let’s say you don’t have your future financial security in mind, nor are you thinking about growing your wealth by investing. The truth is, you’ll almost certainly need to think seriously about money matters in the years ahead. Owning a piece of property can give you a significant headstart.

Of course, there are other reasons to buy a home, the biggest one being your quality of life. If you’ve always envisioned yourself in a place you can truly call your own—where you can renovate to your heart’s content and take pride in ownership—that’s one of the best possible reasons to purchase if you can afford to.

All of that said, there are situations where renting is the better option. Will it put you in financial peril if you buy today? Are you unsure of where you want to be in the near future? Does the commitment of owning (and all the potential hassle and costs associated with ongoing maintenance) feel like a deterrent?

At the end of the day, the decision to buy or rent is a significant one, and it shouldn’t be taken lightly. The good news is, a real estate professional who’s passionate about what they do should be happy to answer your questions—and help you determine whether buying is right for you!

Have unanswered questions about buying a home? We would be happy to discuss them with you. Get in touch here.

5 Questions You’ve Always Wanted to Ask a Mortgage Broker

10.26.21 | For Buyers

5 Questions You’ve Always Wanted to Ask a Mortgage Broker

As a real estate team, one of our most important relationships is with the mortgage brokers we work with. Aside from finding your ideal property, the most significant part of the home buying process is securing a mortgage and payment terms. 

At the Katherine Barnett Team, we work closely with several mortgage brokers. The reason we work with several is that much like choosing a real estate agent, choosing a mortgage broker is a very personal decision. It’s important to choose an individual who gels with your personality and can help you achieve your goals and meet your budgetary needs. 

In this post, we’re talking Agnes Mocko of Mortgage with Agnes and Joanna Skowron of The 6ix Mortgage Group to answer the questions you’ve always wanted to know about working with a mortgage broker. 

1. First of All, What’s the True Difference Between a Mortgage Broker and a Bank?

Joanna: When you go straight to the bank, you only have access to what that particular bank offers, and those mortgage programs may not be in alignment with what you need. However, working with a broker is a one-stop-shop! We collect the same information the bank does, but what’s different is that we have access to the whole spectrum of lenders at our fingertips, which includes the bank you were considering going to!

Agnes: Also, a bank has a certain type of box they need their applicants to fit into, which is why a lot of people get turned down. Mortgage Agents provide expert advice and work alongside their clients throughout the entire process. It’s almost as if you have a Google search engine in your back pocket throughout your entire homeownership journey.


Looking for more first-time homebuyer resources? You’ve come to the right place! Check out some of our other blogs:


2. How Soon Should You Start the Mortgage Application Process when Buying a Home? 

Agnes: You should at least have a conversation with a Mortgage Agent as soon as you begin considering buying a home. The reason for this is because sometimes applications need some tweaking in order to get to the desired purchase price. A good mortgage agent can provide you with advice on how to meet your goal once that time comes. When it comes to a pre-approval, it is important to get one done prior to contacting a realtor. The reason for this is because once you have your pre-approval, you can confidently look for homes within your budget, avoiding any disappointment or wasted time on homes that may not be in your reach. 

Joanna: I would also add that the speed at which a client gets pre-qualified mainly depends on how quickly the required documents get sent over. I would recommend speaking with a mortgage agent about a week prior to house hunting to give a client adequate time to collect their paperwork and enough time for a mortgage agent to input all the information and ask for clarification if need be! 

The great thing about getting a pre-approval is that it offers a ‘rate hold’ that lenders will honour the interest rate the client has been pre-approved for or will adjust the interest rate if it drops for up to 120 days. 

3. Fixed-Rate Vs. Variable: Which Type of Mortgage is Better? 

Joanna: I wouldn’t necessarily say one is better than the other because it depends on what the client is comfortable with. If you’re the type of person who likes to know exactly how much you’re paying each month for peace of mind, I would recommend a fixed rate. If you’re the type of person who is okay with fluctuation in the payment, paying a little bit more or a little less, depending on how interest rates are looking, a variable rate could be the way to go. 

However, generally speaking, variable rates tend to be lower, and historically have shown to be less expensive in the long run.  

Agnes: It’s important to understand the penalties within the mortgage contract when making your decision. It’s quite common to see Canadian homeowners break their fixed mortgages. And fixed-rate penalties use either the greater of three months interest or a calculation known as the “Interest Rate Differential” (IRD). This is the difference between the interest rate attached to your mortgage and how it compares to a current rate that most closely matches your remaining term at that point in time. The issue is no one knows where interest rates are heading, making it impossible to predict. 

Variable mortgage penalties, on the other hand, typically only consist of up to three months of interest. 


Check out more homebuyer resources right here:


4. What’s the Number One Thing First-Time Homebuyers Should Know? 

Joanna: Get pre-approved! In a market where homes are flying off the shelves, it is extremely important to know what your budget is. Something I say all the time is house hunting without a pre-approval is like going shopping without knowing how much money you have in your wallet.

And with this pre-approval, the actual submission of your mortgage application is a lot easier. Because the majority of work has been completed in advance, you won’t have to worry about scrambling for paperwork in such a fast-paced environment. 

Agnes: I would say to get into the market as soon as you can afford it. You can buy a home with as little as 5% down. Be open-minded when looking for your first home. Remember, you are making an investment.

5. What’s the Difference Between a Mortgage Renewal and Mortgage Re-Finance?

Joanna: When the term of your mortgage is close to expiring, you’ll receive a notice from your lender offering you the option of renewing that mortgage with a new rate, and term. It’s a straightforward process stating that you’d like to move forward with your current lender, under the new specifications. 

Agnes: Refinancing a mortgage means you are replacing your existing mortgage with a new mortgage to do things like fund a renovation, take out money to buy an investment, secure a better rate, consolidate debt, etc. 

In order to get the money to refinance, an appraisal needs to be conducted on the home and the current mortgage balance is subtracted from this total. A borrower can then access up to 80% of the remaining amount. However, the borrower needs to qualify for this new mortgage amount.

Interested in learning more about mortgage rules and working with a mortgage broker? We host two webinars with Joanna and Agnes each month! Register for the next webinar here and join us live! 

Everything You Need to Know About Buying a House with a Basement Apartment

10.5.21 | Homeowners

Everything You Need to Know About Buying a House with a Basement Apartment

Basement apartments are an increasingly popular trend we’re seeing among homeowners these days. As housing prices continue to rise, and the housing supply continues to diminish, people are looking for alternative ways to navigate the market. 

If you followed the recent federal election, you’d know that housing affordability was a major part of each party’s platforms. However, policies and laws can only go so far and many Canadians want to take things into their own hands. This is where secondary suites and basement apartments come into play. 

Here’s everything you need to know about buying a home in Milton with a basement apartment…

What Defines a Basement Apartment?

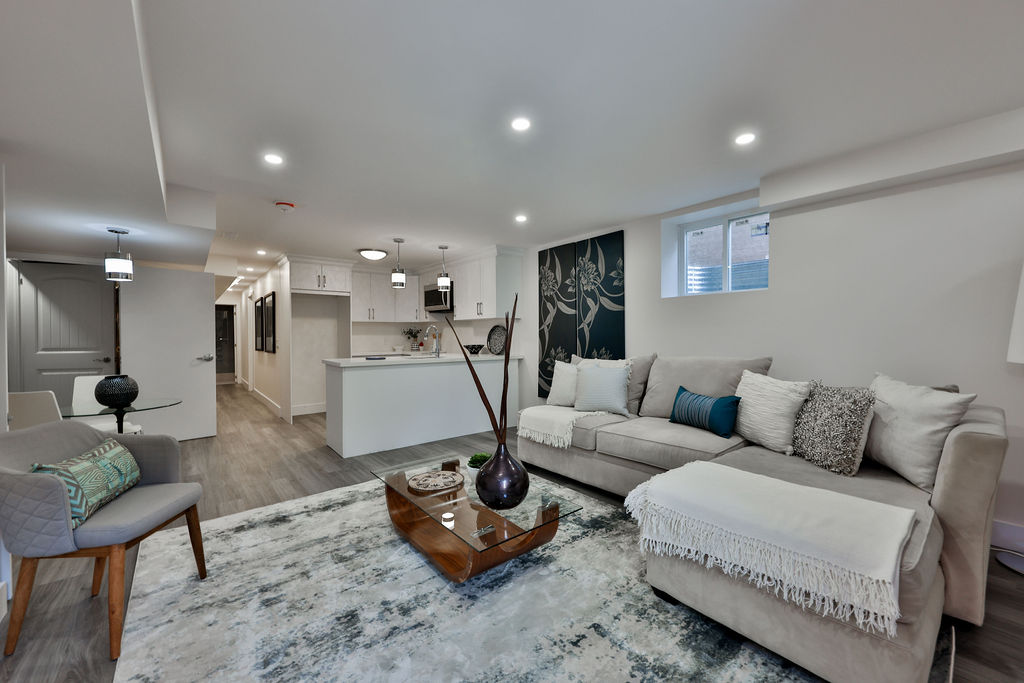
Basement apartments, sometimes also called secondary suites or accessory apartments are defined as a “self-contained dwelling” created by converting a section of the main dwelling into a secondary dwelling. 

Basements make popular accessory suites because it’s often fairly easy and inexpensive to turn a basement into its own apartment. 

What are The Benefits of Basement Apartments? 

Whether you’re a first-time homeowner or an empty nester, there are many benefits to having a basement apartment as part of your house. 

Getting your foot into the real estate market as a first-time buyer can be difficult. As home prices in Canada continue to rise, it’s becoming increasingly hard for young people to afford to buy a home. For these types of buyers, a basement apartment is a great option because it means they can collect rent from a tenant to help supplement their mortgage payments, improving affordability overall. 

Empty nesters can also reap the benefits of a basement apartment. These types of homeowners are typically dealing with excess space in their homes. If they aren’t quite ready to downsize but want to maximize the use of their space and make a little extra money, a basement apartment is a great option. 

Basement apartments are essentially real estate investments and can be used to further your space in the market, give exceptional landlord experience, and help you increase your investment portfolio. 

Buying a House with an Existing Basement Apartment vs. Building New

Basement apartments can significantly increase the value of a home. So if you are in the market for a property with an existing basement apartment, expect to pay a higher price initially. 

However, building a basement apartment might take an initial lump sum investment on your part, but in turn, will increase the property value should you want to sell later. 

If you’re currently in the market for a home, and you know you want to rent out the basement, it’s certainly worth looking into buying a house that has an existing basement apartment. It would save a lot of work and time on your part. 

However, it’s also important to consider the ROI. Do some research into how much building an accessory suite would cost vs. how much rent you could charge in that neighbourhood. This might give you a better idea of whether or not buying an existing house with a basement apartment is better for your unique situation rather than renovating and building your own. 


Ready to buy a home? Get started here:


Thinking About Building a Basement Apartment? Don’t Forget About the Legalities

Building a basement apartment in Milton requires some careful planning and consideration on the homeowner’s part. For example, before you start building, you need to obtain a building permit and ensure your apartment meets certain regulatory standards:

  • The basement apartment must be located in a detached single-family home. 
  • It must have access to municipal sewer and water with either laundry in-suite, laundry connections, or shared laundry services.
  • There must be at least three legal parking spaces on the property.
  • Ceiling height must be at least 6′ 11″ (2.11 m), and 6’5″ under beams
  • It must not be greater than 85m² or 915sq/ft in size. 
  • 45 min floor and wall fire separation (requirements are different in older buildings)
  • The dwelling must have its own private entrance.
  • The home must have a walkout egress or window egress with a minimum 3.8 sq/ft clear opening.
  • The building must have all the appropriate permits and inspections.

Legal vs. non-legal basement apartments is a hot topic in Milton and the GTA. Learn more about it in our blog What Makes a Basement Apartment Legal in Milton here.

How to Maximize Your Basement Apartment Income

Building a basement apartment is more than just sectioning off a part of your home and collecting rent. You are essentially becoming a landlord, which comes with significant responsibility. 

Although no two renters are alike, here are some general features that renters look for in a basement apartment:

  • High-quality appliances and finishes (think, faucets, tub, shower, sink)
  • Higher-than-average ceilings
  • Large, bright windows
  • Nice lighting 
  • Open-concept floorplans
  • All-inclusive utilities 
  • Proximity to public transit, healthcare, grocery, and amenities

Read our quick guide to Milton Real Estate here to learn more about the best neighbourhoods for your unique needs.

It’s also important to attract the right type of tenant for your property. Consider your location and your ideal tenant and ensure that you are doing everything you can to attract that type of person to your listing. It’s also a good idea to complete credit checks and have your tenants fill out applications before agreeing to rent the apartment. 

Did you know we host first-time buyer webinars every month? Sign up to join our next webinar for FREE here.